

Buying an accountancy practice is a big undertaking, and the process is a book in its own right.
This article leans heavily into chapter 12 of The Accountants’ Millionaires’ Club. (Click here to get your copy of the book for free, just pay postage and packing)
What follows is the outline you need to make an informed decision. If you decide to go ahead, take proper professional advice rather than relying on any single article.
a
Most of the work of growing an accountancy firm is about laying firm foundations so you can grow profitably. Acquisition sits alongside that, and it is one of the few growth levers that can add a meaningful chunk of recurring fees to your firm almost overnight. Although this doesn’t make it an easy route to growing your accounting business.
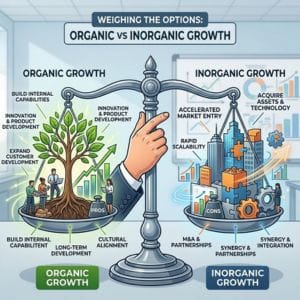 There is a trade off when it comes to buying an accountancy practice. Securing a decent return on investment requires significant personal time from you as the firm owner. Acquisition management demands dedicated focus from you or a trusted senior team member. As a result, you can buy a practice, or in that time you can go after organic growth. You cannot easily do both well at the same time. Buying and integrating another accounting firm takes real focus, and it is very difficult to keep growing your own practice while you are in the middle of that. So the first question is not “can I find a practice to buy?” It is “does inorganic growth serve my plan better than organic growth right now?” Remember, growing your accounting practice means making choices.
When it does fit, accounting firm acquisition can deliver things that organic growth is slow to give you. It adds client fees without the long lead time of winning each client from scratch. It can bring in expertise or a specialism your firm does not currently have. It can make better use of the office space and overheads you are already paying for. So that your overall cost of sales falls or your net profit margin rises as you add fees. All great outcomes to have. But remember you will only generate these outcomes from buying an accountancy practice if the practice you are buying is a good fit.
This is also where I want to manage expectations if you have arrived here looking for a way to scale your accounting practice without working more hours. Over the long run, a well-integrated accounting firm acquisition absolutely can get you there, because you inherit fees and often staff to service them. But the acquisition itself is management-intensive. Before you can enjoy the fruits of what you have bought, you will need to integrate the clients and team members. This means that the hours you are working will go up before they come down. Acquisition is not passive growth. It can be a very stressful way to grow your accounting firm.
Before you get anywhere near an accountancy firm broker or get involved in serious discussions with a firm owner for a private sale, go back to your 3-year Growth Plan and answer five questions honestly.
If the answer to all five is yes, then it is worth seriously considering acquiring fees or an accounting business to boost your accounting firm’s growth.
When you buy an accountancy practice, you are not buying any old thing. You are buying a group of people, clients and staff, who are used to working in a particular way with a particular accountant and firm. It is very tempting to be seduced by a great deal, a practice in distress being sold at a big discount, for example. But that purchase, even if it is a bargain, can still be a bad deal. For example, the purchase doesn’t fit your growth plan. Or your firm does not have the capacity right now to handle the sale and the transition.
Once you know how your accounting firm acquisition suits your growth plan, get specific about how it helps.
When it comes to getting funding for your acquisition, appetite and access are different things. You might be perfectly comfortable taking on borrowing to fund a purchase (i.e., appetite). Only to find the bank takes a different view of your firm’s stability or the quality of the fees you are buying. Or you might be able to raise the money easily (i.e. access), but have no real appetite for the risk. Work out where you stand on both before spending time on a potential accounting practice acquisition. Nothing sours a deal faster than discovering the funding will not come through, or you get cold feet on the potential risk you are taking on.
A good rule of thumb when you are thinking about the value of your accounting practice is to understand how the buyer intends to pay for your firm. Traditional practice acquirers underwrite deals targeting a cash-on-cash payback period of 3 to 5 years. I.e. They want to have paid back the cost of financing and buying the practice within 3 to 5 years. Their way of doing this? Via the cash generated from the newly acquired and integrated practice. The new firm owner typically is looking to keep the new client base for the long term.
In the last 10 years private equity has transformed the accountancy sector. In 2024, research from the ICAEW found that:
Private equity buyers typically have a different business model to an accounting firm buyer. PE houses aim to buy their platform in years 1-3. These are typically fragmented local and regional firms. PE buyers will often pay multiples of 4 to 7 EBITDA.
In years 3-5 they then aim to significantly increase the value of their platform and EBITDA by:
After the PE house has increased the value of their platform they will aim to sell up to a secondary buyout fund or an international or bigger network at a multiple of 8 to 14 times EBITDA.
Accountancy firm specialists broker most sales of fees or whole practices, and most deals move through four distinct stages. Although it is not uncommon to find yourself in a position where you are offered the chance to buy an accountancy practice “off-market”. After all, many accounting firm owners selling up would love to avoid paying the broker fees.
Before we walk through them, set your expectations on time. On average, it takes around five months from start to finish to sell a practice. For smaller practices with less than £100k of fees, that can come down to three to five months. For practices larger than £500k, particularly multi-partner firms, it can run beyond six months.
 Stage one: express interest and establish fit
At this stage, buyers express interest in an opportunity. That normally means signing a non-disclosure agreement and completing a profile of your own firm. The broker sends an anonymised version of your profile to the seller, who then selects potential buyers, and the broker arranges a face-fitting meeting.
Remember that the seller has every incentive to find the right buyer, because a good fit protects the capital value of what they are selling. This alignment benefits both sides. Aim to find an accounting practice that closely matches your own, as compatibility creates a smoother, easier transition of clients and staff later on. During or soon after this first meeting you will be given copies of the seller’s accounts, a schedule of the client accounts for sale and the value of those clients, with client names removed. If it still looks right, you move to due diligence.
This is the stage that protects you. It’s essential to do it properly and not rely on trust or gut instinct. Think of it the way you would think of a survey on a house. You would not buy a property without checking if it is sound. And you should not buy a practice without checking the same. Once you have signed the sales agreement, you cannot easily unwind it. So verify everything the seller tells you.
Due diligence really splits in two. There is the diligence you do to decide whether to proceed at all. And then the deeper diligence you do to finalise the price and the terms.
To make the initial decision, you should expect to see the firm’s:
Once you have taken an initial decision to proceed you will normally be asked to sign a letter confirming you have the funds. And possibly a further confidentiality undertaking,
for example that you will not poach staff if the deal falls through.
The second part is where you dig deep, and a good broker can help you here. If the seller cannot or will not answer a reasonable question, and has no legitimate reason for holding back, treat that as an alarm bell. At this stage you want to check:
One thing you will not usually get access to is anything that could jeopardise the current or future value of the practice if the deal collapsed; such as actual client names or interviews with staff. That is normal, and not something to hold against the seller.
The sales agreement sets out the terms. A big part of it is how and when you pay. Paying in two to three instalments over one to two years is very common, and the larger the practice, the more likely you are to be paying in three instalments over a two-year period.
Itis common to include a claw-back clause, which protects you if clients leave after the sale. These typically work in one of two ways. Either, for every client the seller’s firm loses over a set period, often two to five years, that amount is deducted from the selling price. Or, the clients lost over that period are offset against the value of new clients won, and the net figure is deducted. Either way, the clause aligns the seller’s interests with yours during the handover.
Beyond payment and claw-back, the agreement needs to settle
You have just paid a large sum for a practice. This is where you do the work to realise the value you have paid for the accounting firm.
Your transition plan needs to cover three things:
As part of your planning, expect to lose up to 15 per cent of the client portfolio.
The best way I have found to describe a transition is that it is a bit like a marriage with children. Like any good parent, you want to be on your best behaviour in front of the kids. Which here means the staff and clients affected. And you want to be certain you are communicating the same messages to every stakeholder: staff, clients and the seller alike.
 Do not underestimate how long it takes to get to know clients you have inherited. Clients are people. And people do not like to feel they have been sold. In practice most are understanding, but the handover has to be handled with care. A good approach is for the seller to write to each client explaining the change in ownership and suggesting a meeting between you, the seller and them. The letter should make clear when the seller will be available until, or whether they can still be contacted. Your seller will be able to flag the sensitive clients, and for those you should build a special transition plan together. For example the seller phoning them before the letter lands to reassure them. This is exactly where a claw-back clause earns its keep, because it gives the seller a strong incentive to stay involved and make the handover smooth.
Your due diligence will have shown you the gap between your fee structure and the seller’s. If the seller’s fees are lower than yours, it is usually worth keeping them static for a year. This gives you the time to handle the transition and build a relationship with each client. Then aim to bring their fees into line with your expectations once you have built the goodwill. Push fees up too fast and you turn an inherited client into a lost one.
Then there are the people. When you buy an accountancy practice, you are not only taking on clients; you are often taking on staff. And that brings its own questions.
A staff member could leave and take clients with them. When buying an accountancy practice, you are particularly susceptible to this risk. If that happens, your claw-back clause would probably protect you financially. But if this happens, a good deal can become a much less good deal. Retaining key people is normally part of the deal.
Many accounting firms that adopt a buy and build growth strategy will get caught out by this. When you are buying blocks of business from £50k to £400k, you will often only be buying the client bank. Or if you do inherit team members as part of the acquisition, they may be at a fairly junior level. Which means you can quickly grow an accounting business where every team member reports to you. Which is fine up to £250k in revenue. After this point, your structure will break. Or, even worse, every client wants to talk to you, not a team member.
Part of your transition plan needs to include how your integrated accounting firm will be structured. For example:
 Case study: How Sian used a buy and build strategy to grow her accounting business
Sian Kelly, owner of Inform Accounting, bought a small practice from a local accountant. The accountant was over 70. They would probably have sold up sooner had his daughter not been working in the business.
Because the client base was ageing, Sian was able to pick the practice up for a low multiplier of GRF, with a decent claw-back clause. Her seller put one condition on Sian. She had to take on the owner’s daughter, who had been the day-to-day contact for most of the clients. Keeping the daughter on meant the clients kept a familiar face through the change. To protect her investment, Sian made a point of helping her integrate into the wider firm. There was space in the office, so adding headcount was no problem.
The transition itself was handed to a team member to project-manage. I.e. specifically the job of moving the new clients onto the cloud and onto the firm’s preferred ways of working. The inherited clients were on lower fees than the buyer’s normal rates. So the decision was taken to keep those fees static for a year and bring them into line over 12-24 months after the acquisition.
Buying an accountancy practice can help you grow rapidly. Potentially all the way to a seven-figure firm. But it is not the right growth route for every firm. The right answer to “should I use accounting firm acquisitions to grow my accounting firm?” is “it depends on your plan, your timing and your capacity.”
If you are the owner weighing acquisition against organic growth, the deciding question is which route genuinely gets you to your 3-year Growth Plan faster and at acceptable risk. But also keeping in mind everything else you currently have on your plate. If you’re an owner who’s been offered a practice out of the blue, the deciding question is whether this particular practice fits that plan. Or whether it is simply an opportunity that happened to land in your lap. Remember, an opportunity is only a good opportunity if it fits your plan to grow your accounting business.
 Written by Heather Townsend. Heather has been helping accountants grow their practice for 20+ years. She is the founder of The Accountants’ Growth Club and the author of 6 books, including The Accountants Millionaires’ Club, Profitable Pricing For Accountants and The Go-To Expert. Heather designs training programmes for the club and provides high-level coaching.