Sorting out your business development

Most accountancy firm owners didn’t get into this business because they love sales. But if you want to grow, you can’t avoid it forever.

The trouble is, business development for accountants often feels like feast or famine. You’re either too busy delivering client work to chase the next one, or scrambling because the pipeline’s run dry.

One of the first things we work on with our AGC members is building a business development engine that runs without you having to constantly fight fires.

This means having a clear strategy and knowing what to prioritise, rather than reacting to whatever’s loudest that week. It’s why one of the 6 profit pillars we check in our free Growth Assessment is Pillar 6 – Growth Strategy & Priorities.

From “I’ll think about it” to “Where do I sign?”: The sales process for accounting firms that actually works

Written by Becky Rogers, copy and content writer for Accounting firm owners and Accounting specialists.

You’ve had a great chat with a promising lead. They seemed interested, the rapport was high, and then comes the phrase that kills the momentum: “I’ll think about it”.

They never get back to you.

For many accountancy firm owners, this isn’t just a missed opportunity, it’s a sign of a deeper struggle. You’re brilliant at the work, but you avoid “selling” because you refuse to be the pushy, “used car salesman” stereotype.

The result? You waste hours on “tyre kickers,” suffer through feast-or-famine revenue, and lose high-value clients who were actually ready to buy.

The truth is, you don’t need to be pushy; you need a sales process for accounting firms that does the heavy lifting for you. It’s time to stop doing free consultancy and start using a structured system that qualifies leads, builds undeniable value, and makes saying “yes” the only logical next step.

Why “I’ll think about it” means you failed earlier

When a prospect says they need to “think about it,” it’s rarely because they actually need time to ponder. It’s usually a symptom that you failed to surface a real objection or establish value earlier in the meeting.

Translation: you didn’t build enough distance between where they are now (pain) and where they want to be (gain).
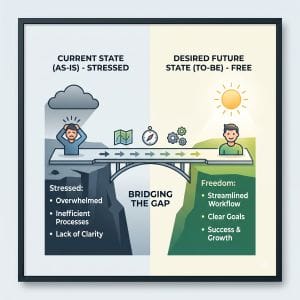
The As-Is vs. To-Be gap

Diagram showing the distance between an accounting lead's current pain and their future business goals.When a prospect says they need to “think about it,” it’s often because you haven’t established enough distance between where they are now (pain) and where they want to be (gain). Your job is to bridge that gap by asking questions that pivot from business mechanics to personal impact.

The “To-Be” State (The Gain) 

Don’t just ask about their accounts or tax; ask about their vision. Use these questions to identify their true motivations:

  • Business Aspirations: “What is your business trying to achieve, and why is that motivation important now?”
  • Personal Freedom: “How will your life be easier when the business reaches this goal? What does that mean for your partner and family?”
     
  • Future Security: “What would doubling the capital value of your business on exit mean for your pension and retirement?”

The “As-Is” State (The Harsh Reality) 

Once you’ve helped a lead identify their dream “To-Be” state, you must bring them back down to Earth with a large bump. If you don’t increase this distance, your fee will feel like a “cost” rather than an investment in a solution.

This is your moment to really dig into their current situation and escalate the pain they are feeling right now. Use these questions to surface the truth:
  • Financial Reality: “Tell me about your profits. Do you really have enough to take the income you want out of the business?”
  • Operational Friction: “What are the weak links in your current organisation? What have you tried and failed with previously?”
  • The Cost of Inaction: “What is the impact if you do nothing or delay? What will happen if you can’t overcome this?”

An older man with short grey hair and glasses smiles warmly. He is wearing a checked shirt with red, blue, and white stripes, standing indoors in front of a window with white frames.Case study: How Guy turned a £10k Inquiry into a £23k Result

This is how Guy Robinson, founder of Xebra Accounting, used the As-Is/To-Be process to double a fee in one meeting.

  • The Problem: Guy received a referral for a standard setup. The initial scope suggested a £10,000 annual fee for bookkeeping and year-end accounts.
  • The Action: Instead of quoting a price, Guy dug into the “As-Is” state. He discovered the current accountant had made a mess of their cloud setup, leaving the owners with zero management info and no way to grow.
  • The Result: By uncovering the true pain and business aspirations, Guy closed a £21,000 annual recurring fee plus a £2,000 one-off fee to fix their systems.

“If I hadn’t spent so much time digging into their As-Is and To-Be, I doubt I would have come away with such a big fee.” – Guy

This case study is an extract from the Accountants’ Millionaires’ Club Book. Get your copy for free here (just pay postage and packing)


A quick note on surfacing objections

A good technique to help identify what your lead’s objections are is to proactively tell them some of the objections that other clients had before they were signed up.

For example:

“Although our costs are higher, all of our clients have remarked after implementation that they now realise that our solutions are well thought through, and therefore there’s no tidy-up or refinement necessary afterwards.”

When faced with one of these difficult questions, you want to let them know that not only do you understand why they feel that way, but that they’re right, and others have in the past felt that way. You’re not being defensive, but reinforcing the fact that they’re right.

You also need to show them that clients who had been in exactly their situation managed to gain a positive outcome by working with you. This is called the Feel, Felt, Found technique.

Example:

Feel: I understand how you feel about doing tax planning.

Felt: Many of my other clients, when they were in the same situation as you, felt the same way and were wondering whether they should ditch tax planning altogether. They were really concerned that their actions would be viewed negatively if it got out into the public domain.

Found: However, when we’ve worked with clients in exactly the same place as you now, we’ve found that they’ve been able to significantly reduce their tax bill by us helping them find ethical ways to reduce it, such as R&D tax credits.

a

The sales process for accounting firms that actually works

The most effective sales process for accounting firms is a four-stage diagnostic framework consisting of (1) rigorous lead qualification using the DUFF model, (2) a ‘velvet rope’ pre-qualification filter, (3) a value-based discovery meeting focused on ‘As-Is vs. To-Be’ gap analysis, and (4) a structured follow-up system that prioritises micro-commitments over pushy sales tactics.
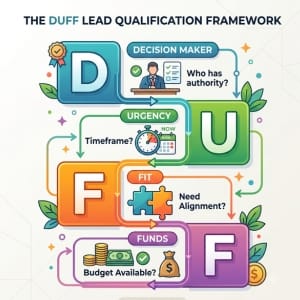
The DUFF framework for qualifying accounting leads: Decision Maker, Urgency, Fit, and Funds.

1. Qualify leads and weed out bad fits using the DUFF Framework

Possibly the biggest business development time waster is generating and progressing the wrong sort of leads – the people who are never going to become a client, or if they do sign up, are not the type of client that your firm wants.

The fastest growing accounting firms are often the ones most picky about who they take on. Use the DUFF framework to rigorously qualify leads before you invest hours in proposals:

D – Decision Maker

The Goal: Ensure you are talking to the person with the authority to allocate funds.

Key Question: “Who else in your organisation needs to sign off on this project?”. 

Very often the person who enquires about using your firm is not the ultimate decision maker. Whilst they may seem to have the right title, it may not always be the case. That’s why it’s essential that you find out if you’re talking to the organ grinder or the monkey. For example, family-owned businesses often need the approval of more than one family member to change accountants. 

U – Urgency

The Goal: Confirm the prospect is motivated to act now and has a specific timeframe.

Key Question: “What will happen if you decide not to go ahead with this work?”.

When someone buys a service from an accountant, this normally represents a considered purchase. There’s a high level of risk (be it money or reputation) as a result of using your services. Before your firm allocates a large proportion of time to developing a piece of business, you need to make sure the lead intends to make a purchase and has a specific timeframe for doing so.

If they don’t have a specific timeframe or a burning platform, they’re likely a tyre kicker.

To find this out, you could ask multiple questions:

  • When do you want to get started?
  • What else is a priority in your organisation which may delay the start of our work together?
  • How urgent is this piece of work for you and your team?
  • What will happen if you decide not to go ahead with this work?
  • Do you have any internal deadlines which you need to hit which this work will impact?
  • What could stop the two of us working together?

F – Fit

The Goal: Identify if there is a personality match and if your firm can truly solve their specific problem.

Key Question: “What are you looking for from your ideal accountant?”.

Not every client and accountant pairing will be a match made in heaven. Many an accountant has found they’ve signed up a Pain-In-The-Arse (PITA) client due to a lack of rapport between them and the client. If the rapport isn’t there? Walk away.

In addition to a good level of rapport, you need to ensure the lead has specific needs your firm can address. The initial presenting problem is often not what your firm ends up solving after some investigation.

F – Funds

The Goal: Determine if the lead can afford your firm’s services.

Key Question: “What budget have you in mind for this piece of work?”.

As early in the sales pipeline as possible, you want to ascertain that the person has the financial capacity or access to the funds to buy from your firm.

Don’t be afraid to give a broad price range early (e.g., “Clients with problems like yours typically invest between £5k and £10k”) to filter out those who can’t afford you.

If they state that they don’t have a budget, this may not be Game Over, but indicates that you will need to decide whether you want to educate them as to the value of your services.

Take our free Growth Assessment to see exactly what is hindering your ability to win high-value clients. It covers the 6 Profit Pillars of business growth and takes under 15 minutes to complete

Relevant articles

Barriers to growing your firm

Without a steady stream of new clients and a clear plan to win them, growth becomes a matter of luck rather than design. This is why one of the 6 profit pillars we check in our free Growth Assessment is Profit Pillar 6 – Growth Strategy & Priorities. 

To see whether your issue is just with business development or a bigger more systematic problem, take our 10-15 min free Growth Assessment here.

Helpful resources

Download our free SALES PROCESS MAP to make sure you never waste time on a tyre kicker and never leave business on the table. Click here.

Download our free client persona template to focus your marketing and communications to attract the right type of clients. Click here. 

Use the exact same script our members use to get in touch with old prospects and turn them into clients of the firm. Click here.


Want to go deeper?

Get a free copy of The Accountants’ Millionaires’ Club book (you just pay for postage and packaging). 

Chapter 11 talks about how to turn your Leads into paying Clients.

Chapter 15 shows you how to create and resource your firm’s Tactical Marketing Plan.

Chapter 16 covers how to grow your firm’s Client base.

Order your free copy here.

a

2. Pre-qualify leads before the discovery meeting

Stop doing free consultancy for everyone who calls. Implement a “velvet rope” entry policy to protect your time.
A woman with grey curly hair in a suit sits at a desk with a laptop, holding her temples and looking stressed. Papers, a mug, and office folders are visible in the background. This image represents the stress of leading a growing accounting firmThe Questionnaire Filter

Before booking a meeting, ask the prospect to complete a Potential New Client Questionnaire. If they can’t be bothered to fill it in, they’ll be a poor client who won’t answer your emails later.

The 10-Minute Triage Call

Conduct a short 10-15 minute phone call to check they’re a good fit. Use this to explicitly state your minimum fees (e.g., “We don’t take on clients under £X”). This weeds out price shoppers immediately.

The “Pitch Pack”

Send a pre-meeting pack that includes case studies and a checklist of information they need to provide (e.g., last accounts). This positions you as an expert and tests their commitment.

Your pitch pack should include:

  1. Your business card
  2. A letter confirming when you will meet, who they will be meeting and venue for the meeting (include helpful details for them to find the venue and where they can park)
  3. Your checklist of what information they need to send through before the meeting
  4. Testimonials and case studies from happy clients who are representative of the prospective client
  5. A list, including photos and direct line phone numbers, of potential key contacts for them and their business
  6. An outline of your firm’s pricing packages which are relevant to their business
  7. Sample reports of representative businesses to demonstrate your firm’s reporting capabilities (if appropriate)

3. Build value and urgency in the sales conversation

Transform your sales meetings from “chats” into diagnostic consultations.

The 50% Rule

Spend at least half the meeting listening and fact-finding about their business and personal objectives, not talking about your services.

When you meet:

  • Introduce yourself very briefly (under a minute)
  • Things may have changed since you last checked, so clarify how much time they have for the meeting, that the agenda is still appropriate, and what they want to achieve by the end of the meeting
  • Explain that you’re keen to understand more about them and the organisational reasons behind this meeting taking place, particularly what has motivated them to talk to you about becoming their accountant
  • Allocate at least 50% of the meeting time to listen and explore their problems
  • Summarise to check understanding of what you’re hearing
  • Identify the risks for the client of doing nothing, plus the value your firm can bring by working with them
  • Find out the criteria that they will use to select a new accountant
  • Uncover their timings and anything that will affect their ability to proceed quickly
  • Suggest some potential solutions, and cost these solutions if requested
  • Find out any resistance or objections they may have to working with you
  • Agree any next steps and ask when they would like you to follow up with them if you have not heard anything

Finding the “Why”

Ask the two most powerful questions: “What prompted you to get in touch?” and “What motivated you to start your business, and has that changed?”

These are the two most powerful questions any accountant can ask their clients. The follow-up is exploring their current reality.

We asked “What motivated you to start your own business?” at a webinar at Accountants’ Growth Club. The majority of members answered “to be my own boss” and/or “to work less hours than I would in industry.” When we explored their current reality, 100% of them said they’ve found the opposite to be true. They’re actually working more. If this is you, then take our free Growth Readiness Assessment to see what are the real root causes for you working long hours.

This isn’t just a local issue either; surveys show that over 60% of business owners report working significantly more hours than they intended, with the vast majority spending their time on administrative ‘whirlwinds’ rather than high-value growth activities.

This gap between expectation and reality? That’s where the sale happens.

Want to learn how to build this systematic approach to winning new business? 

Our New Business Accelerator  is a 15-week programme that teaches you exactly how to have these conversations and convert leads without feeling pushy. One of our current members used to post on LinkedIn once every five years. Now, thanks to this programme, he is posting three times per week and winning one to two new clients every single week.

*Members typically add £40k-£60k of new business during the programme.

 a

The Four Freedoms

Listen for their true drivers. Every business owner is motivated by a lack of Time, Cash, Mind (stress), or Control. Frame your solution as the key to unlocking these freedoms.

If you’re dealing with freelancers and contractors, control is going to be very high. They want to be able to choose what they do. If you’re dealing with a very busy business owner, time and cash are big issues for them, maybe even mind as well.

It’s about really understanding what their drivers are. Why are they trying to grow their business? Why did they want to become a contractor? What was it all about for them? Was it to get a mortgage quicker to have their own home? To start a buy-to-let business? To retire at the age of 30? What was it?

Selling benefits, not features

To move a lead toward a “Yes,” you must stop selling “what you do” (the features) and start selling “what they get” (the benefits). A feature is just a fact about your firm; a benefit is the positive outcome the client actually cares about.

When you understand the specific benefits they crave, you can tailor your service to meet those needs. Here is how to reframe your firm’s value in your next conversation:

  • Don’t just say you’re a “Specialist for Retail Businesses.” Do say: “Because we work exclusively with retail clients like you, we already know the strategies that will grow your business, which KPIs to monitor like a hawk, and which apps will take the headache out of your daily books.”
  • Don’t just say you’re a “Small/Boutique Firm.” Do say: “Being a smaller firm means you will be a major priority for us. You won’t be passed to a junior; you’ll receive a high level of personalised service from someone who truly knows your business.”
  • Don’t just say you’re a “Local Firm.” Do say: “Being local means we are close enough to meet face-to-face whenever you have a sensitive issue that needs a more personal touch.”
  • Don’t just sell “Management Accounts.” Do sell: “The data and confidence you need to safely hire that new sales director or expand into your next location.”
  • Don’t just sell “Tax Planning.” Do sell: “The peace of mind that comes with knowing you won’t get a surprise bill and that you are keeping more of your hard-earned money ethically.” 


4. Follow up (without being a pest)

“There are no great meetings, only great follow-up.” Don’t let your lack of a follow-up lose you a lead. Make it into a process.

Micro-Commitments

Design your process to get small acts of commitment from the lead. Ask, “What do you see as the next step?” or “When should I follow up if I haven’t heard from you?” This puts the ball in their court.

Your aim when managing your firm’s leads through your sales pipeline is to let them set the pace, but also design into your sales process for accounting firms little acts of commitment from them to take them to the next stage. These acts of commitment enable your firm to focus on the leads who are committed to proceeding and eliminate the tyre kickers.

The 24-Hour Rule

If they ask for a proposal, get it to them within 24 hours while the emotion of the meeting is still fresh.

Send your proposal to your client within 24 hours of the business development meeting. The sooner your client can receive your proposal, the quicker they can sign it off.

Most clients are really impressed if their potential new accountant can get them a proposal within 24 hours, as this is far from the norm. Software such as Practice Ignition will help your firm automate the proposal process.

Clients are more likely to accept a proposal if it mirrors what you were talking about in the meeting. There should be no surprises. If you can use your firm’s pricing tool with the clients in the meeting, this will help reduce any friction in accepting your proposal.

Nurture, Don’t Pester

If the timing isn’t right, move them to a “keep-in-touch” list.

If your firm has done everything right up until this point, there’s no reason why the lead may not press the Go button again. The challenge your firm faces is to stay in touch with this lead until they’re ready to press Go. This means standardising your firm’s keeping-in-touch processes.

For example, you could send them valuable content (blogs, guides) that helps them, rather than “just checking in” emails. This keeps you top-of-mind for when they are ready.

At the Accountants’ Growth Club, we’ve refined a sales process that every one of our members uses. Download our sales process map for free here.

a

Sales training for people who hate sales

If you’re like most people, you probably hate being sold to. As a result, you fear becoming that salesperson. You didn’t become an accountant to be a salesperson. But you must become a “rainmaker” to grow. 

Recent industry research from the 2024 State of the Accounting Profession Report indicates that while ‘acquiring clients’ is a top priority, the lack of a formal sales process is what prevents most firms from scaling effectively. That’s likely because many still rely solely on passive referrals rather than a structured process.

So how do you make sure sales happen (especially if you and/or your team hate it)? Here is our advice:

Smiling woman with grey hair sits at a café table with a laptop, mobile phone, teapot, cup of tea, and a jar of sugar. She wears a white jumper and a smartwatch. Green chairs and plants are visible in the background. She represents an accountant successfully converting a high-value lead using a structured sales process.

Reframe “Sales”

Stop thinking of it as selling. Reframe the activity as “helping your clients to buy”. You’re diagnosing a problem and offering a cure, not pushing a product.

Handle objections with the Feel, Felt, Found technique

When a client pushes back on price, don’t get defensive. Use this script:

“I understand how you feel about the fees. Many of our other clients felt the same way initially. However, they found that the tax savings/growth we generated covered the fee multiple times over.”

The “If… Then” Technique

If a client has a specific barrier (e.g., price), isolate it.

“If we can resolve the budget issue by adjusting the scope, would you be happy to proceed?”

This identifies if the objection is real or a stalling tactic.

See pushback as a request for reassurance

The reasons why a lead will decide not to work with your firm boil down to only three:

  • They don’t believe your firm is capable of doing the work
  • They don’t believe that they’re getting good enough value if they work with your firm
  • There’s not a good relationship fit

When you realise this, it becomes easier to anticipate their concerns and how these will be articulated.

For example, if you’re asked “What sort of results have you achieved with previous clients?”, this is the lead testing your capability to be able to help them. Answer the difficult questions by using one of your credibility stories.

These difficult questions aren’t because your lead is being awkward. Normally they either want to be reassured about something or to find out the answer to something.

Changing your mindset to view difficult questions as just a request for more information helps you be more relaxed in a sales meeting. It also helps you see that things like “Your fees are quite pricey” as a signal that they think the price is higher than your competition.

a

Stop losing leads to a bad sales process

You didn’t become an accountant to be a “pushy salesman,” but you also didn’t start your firm to work more hours for less profit than you made in industry.

Every time you hear “I’ll think about it,” it isn’t just a missed lead; it’s a symptom of a sales process that is failing you. Every “tyre kicker” who wastes your time is stealing minutes away from your family, your growth, and your peace of mind.

The most successful firm owners aren’t the loudest talkers; they are the ones who respect their own expertise enough to qualify ruthlessly and lead with value.

You have the skills to change your clients’ lives. Now, you just need a sales process that does the heavy lifting for you. Don’t let another high-value lead walk away because of a “chat” that should have been a consultation. It’s time to stop selling and start helping your clients buy.

a

Frequently Asked Questions (FAQs)

How do I stop prospects saying "I'll think about it"?

When a prospect says they need to think about it, it usually means you haven’t surfaced their real objections or established enough value. To prevent this, you must clearly define the gap between their current problems (the pain) and their future business goals (the gain).

This technique bridges the gap between a client’s harsh current reality (the “As-Is” state) and their ultimate business and personal goals (the “To-Be” state). By magnifying the distance between the two, your fee transforms from a simple business cost into an essential investment in a solution.

The most effective sales process for accounting firms is a four-stage diagnostic framework. It involves rigorous lead qualification (using the DUFF model), a ‘velvet rope’ pre-meeting process, a structured discovery meeting focused on the client’s pain points, and a seamless proposal presentation.

Accountants should proactively address objections before the client brings them up. A highly effective method is the “Feel, Felt, Found” technique. Acknowledge how they feel about the price, explain that other clients felt the exact same way initially, and then share the positive results those clients ultimately found.

You stop giving away free consultancy by shifting the focus of your sales meetings from tactical advice to diagnosing the client’s core problems. Ask deep, probing questions about their operational friction and the true cost of their inaction, rather than immediately telling them how to fix their books.

If you’re serious about standing out and attracting the right clients, our New Business Accelerator is a 15-week programme that helps accounting firm owners add £40k-£60k of new business by implementing exactly these strategies with expert support and accountability.

Head shot of Becky Rogers content writer for growing accounting businessesWritten by Becky Rogers. Becky has spent the last 10+ years writing copy and content for Accounting firm owners and Accounting specialists. Over the last 5 years she’s written copy for over 30 accountants’ websites. Connect with Becky on LinkedIn.